Things come together and not in a good way
The war rumbles on. The market is realising that inflation will be higher for longer, this focuses everyone on the problems- high government debt and half a trillion of AI bonds.
Why are rates up so much! The war’s influence continues and it’s still hot.
The focus has just moved from Hormuz where non-Iranian oil is moving almost at pre-war volumes, but Houthis cut the pipeline to the red sea, captured islands in the Red Sea threatening (oil) traffic.
Oil means inflation means higher rates. US longer term rates are strongly correlated with oil prices now.
The US economy gives mixed signals, weak jobs, then strong jobs, then weak jobs.
But the Fed is committed to cutting inflation. The inflation signal is unambiguous, so raised Fed Funds target by 25bps to a range of 3.75%-4.00%.
The war story is not over, even if oil flows in Hormuz in spite of the Iranians.
The markets are realising that inflation will be higher for longer. We can see inflation in the headlines – diesel prices, but we also have weather affecting softs as well as fertiliser and fuel costs pushing up farmers’ costs.
We must not forget the longer-term effects of the damage to Russian refining capacity and to LNG facilities in the Gulf.
Oh, and don’t forget copper: at record highs as tariffs, AI demand and weak production come together.
This inflation story gets minds focused on Government debt and deficits – which are problems in almost all developed countries.
As well as needing record levels of treasury issuance for refinancing and interest next year, the US market will also have to find demand for around $500bn of data centre cap ex financing.
It is easy to catastrophise and forecast rates rising further. However, yields are now off recent peaks, so perhaps for now we will have a respite. What is important to bear in mind is that even if longer term rates don’t rise much further – the world has changed. The cost of capital has changed. It will not fall again soon.
One story which is not in the press is one from earlier in the year- the end of the dollar carry trade: speculation was that as the Japanese interest rates reached the 3% mark, this would spark mass repatriation of funds to Japan and the selling of US treasuries. The 10yr JGB has broken through the 3% yield mark. Perhaps this is a feature too.
Whatever the combination of factors and sentiment, we find ourselves with US interest rates at levels not seen since 2002.
The impact on equities has not been good!
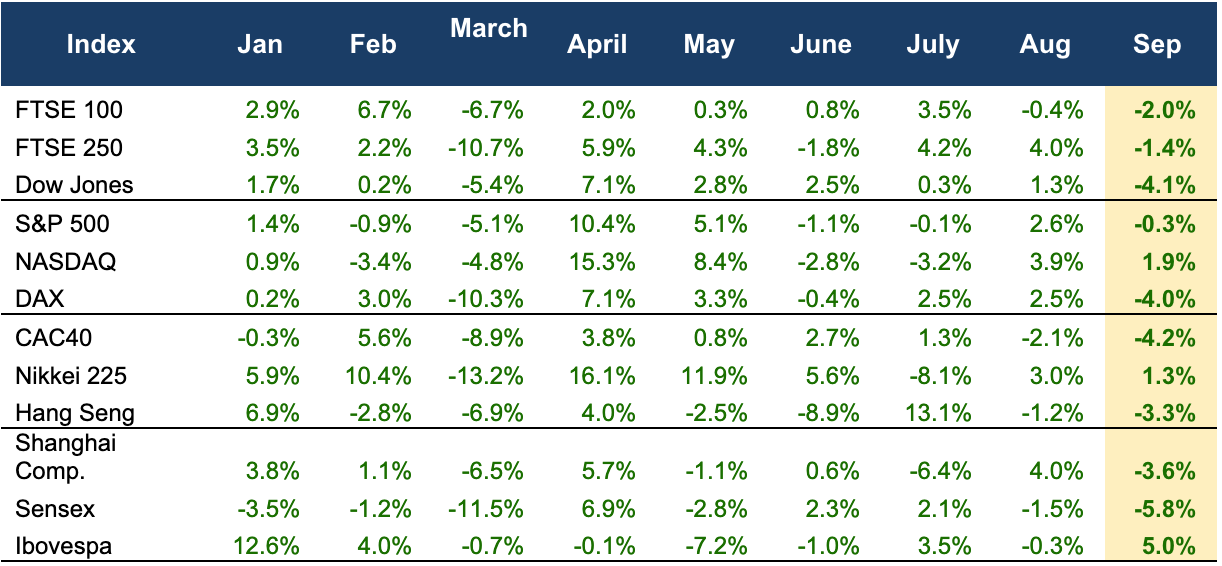
The month has been poor for equities with only tech moving ahead. Positive news from Meta gave the Mag7 a spurt pushing them into positive territory for the year again, having only been in the black this year for six weeks or so around June. News from Samsung spurred a wider rally in the chip stocks.
Unfortunately, what investors want to see is strength broadening. It is not. Non-AI/Chip companies are facing higher debt costs and inflation.
The tech/chip rally has also benefited Global funds in that the Korean Kospi index and Japan’s Nikkei 225 have both risen around 5% over September.
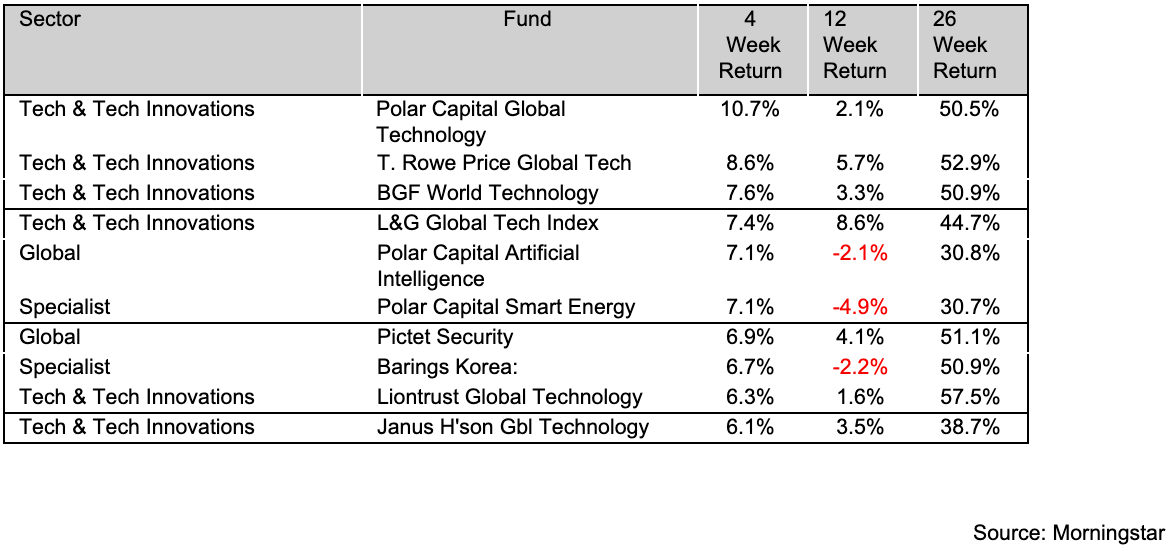
The best performers over the last 4 weeks
Precious metals
Rising yields are punishing gold and silver. The excitement following Bessent’s failed interest rate suppression last month has gone. Gold down! Silver down!
Our portfolios
So how have the portfolios performed?
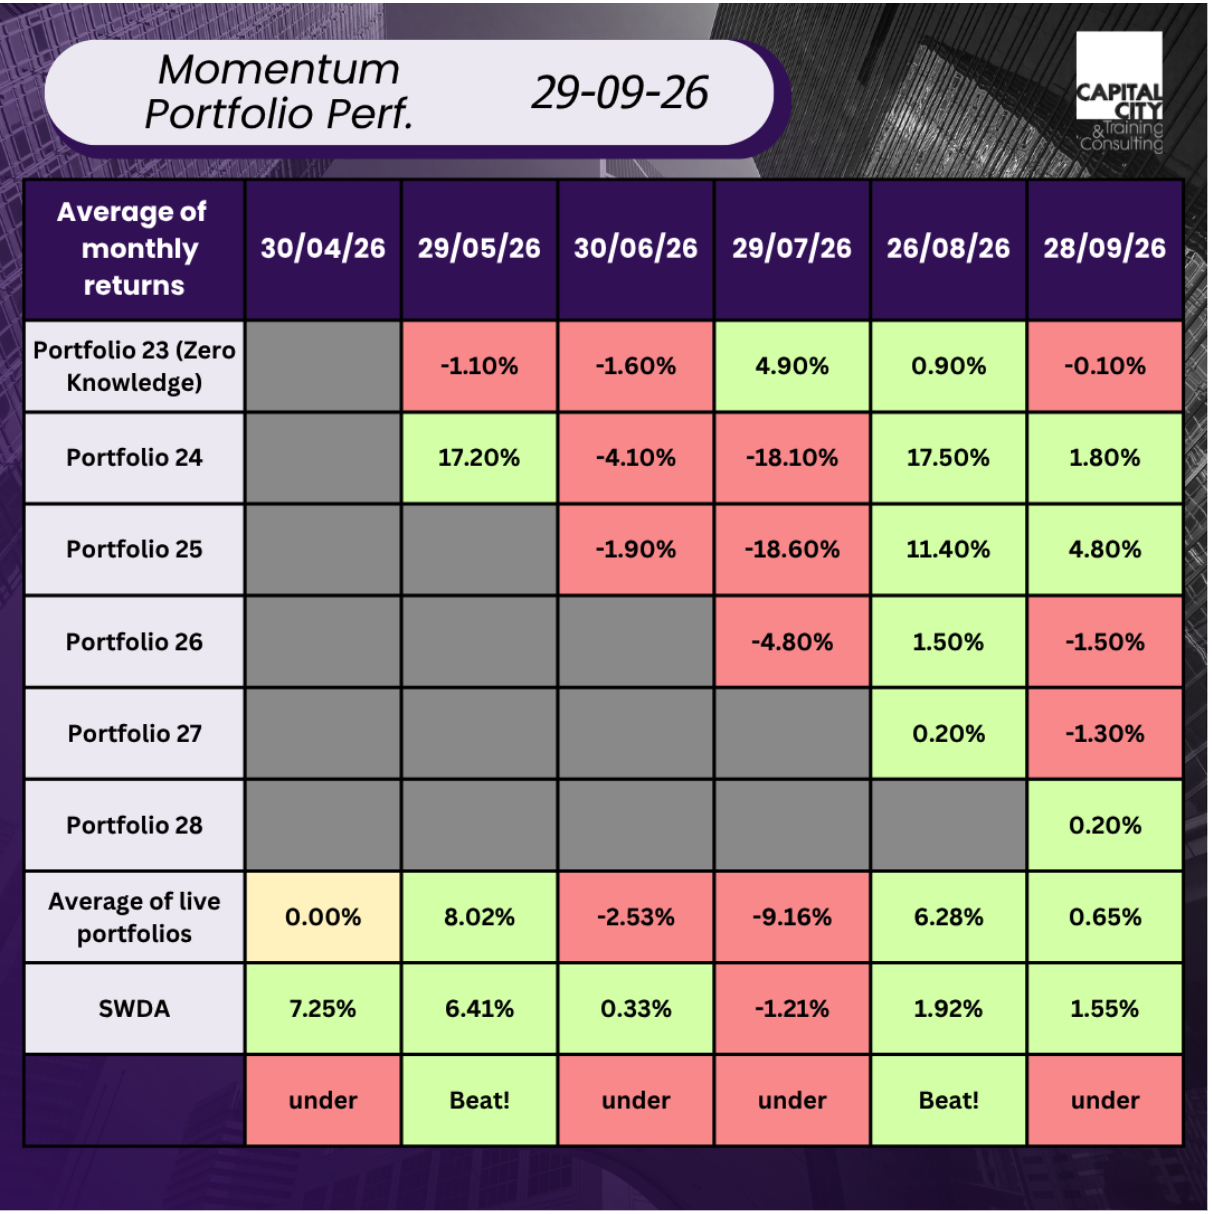
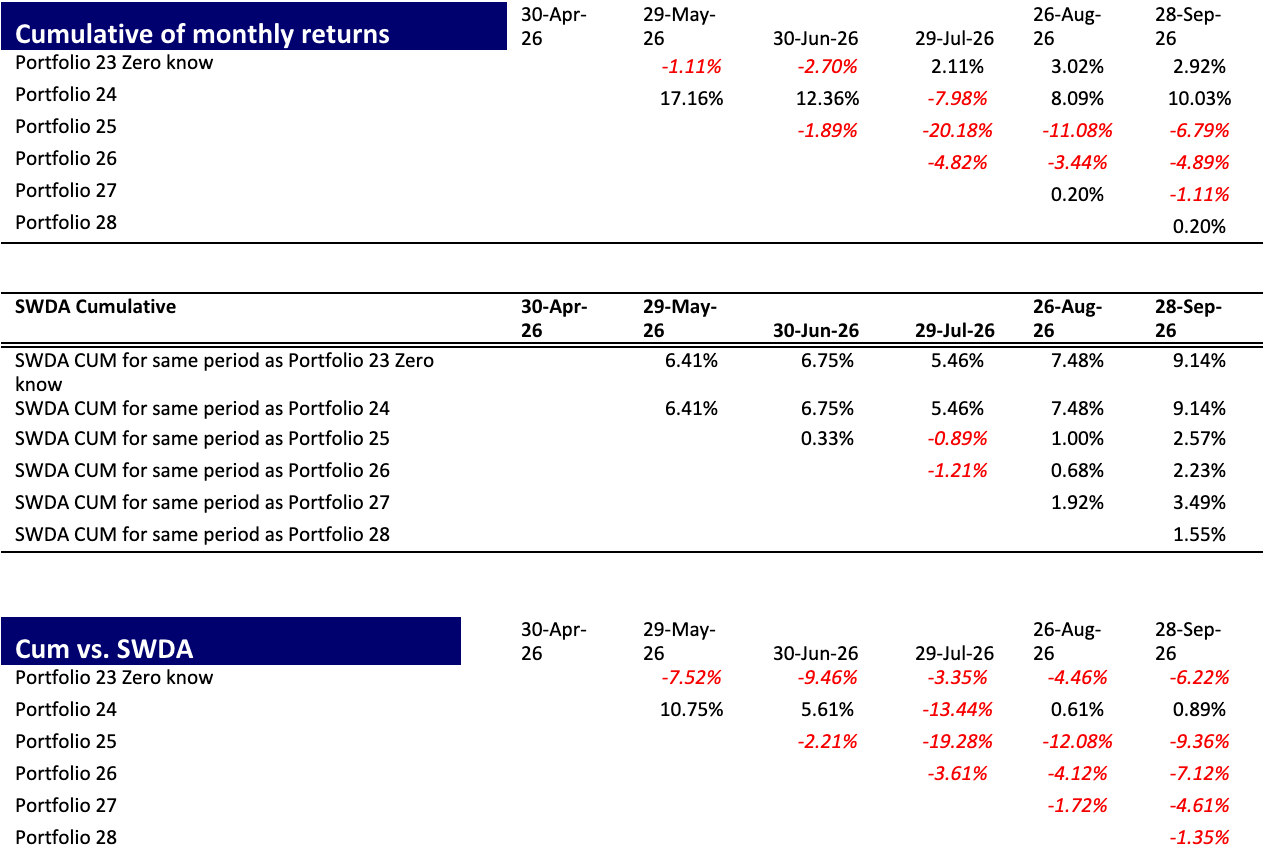
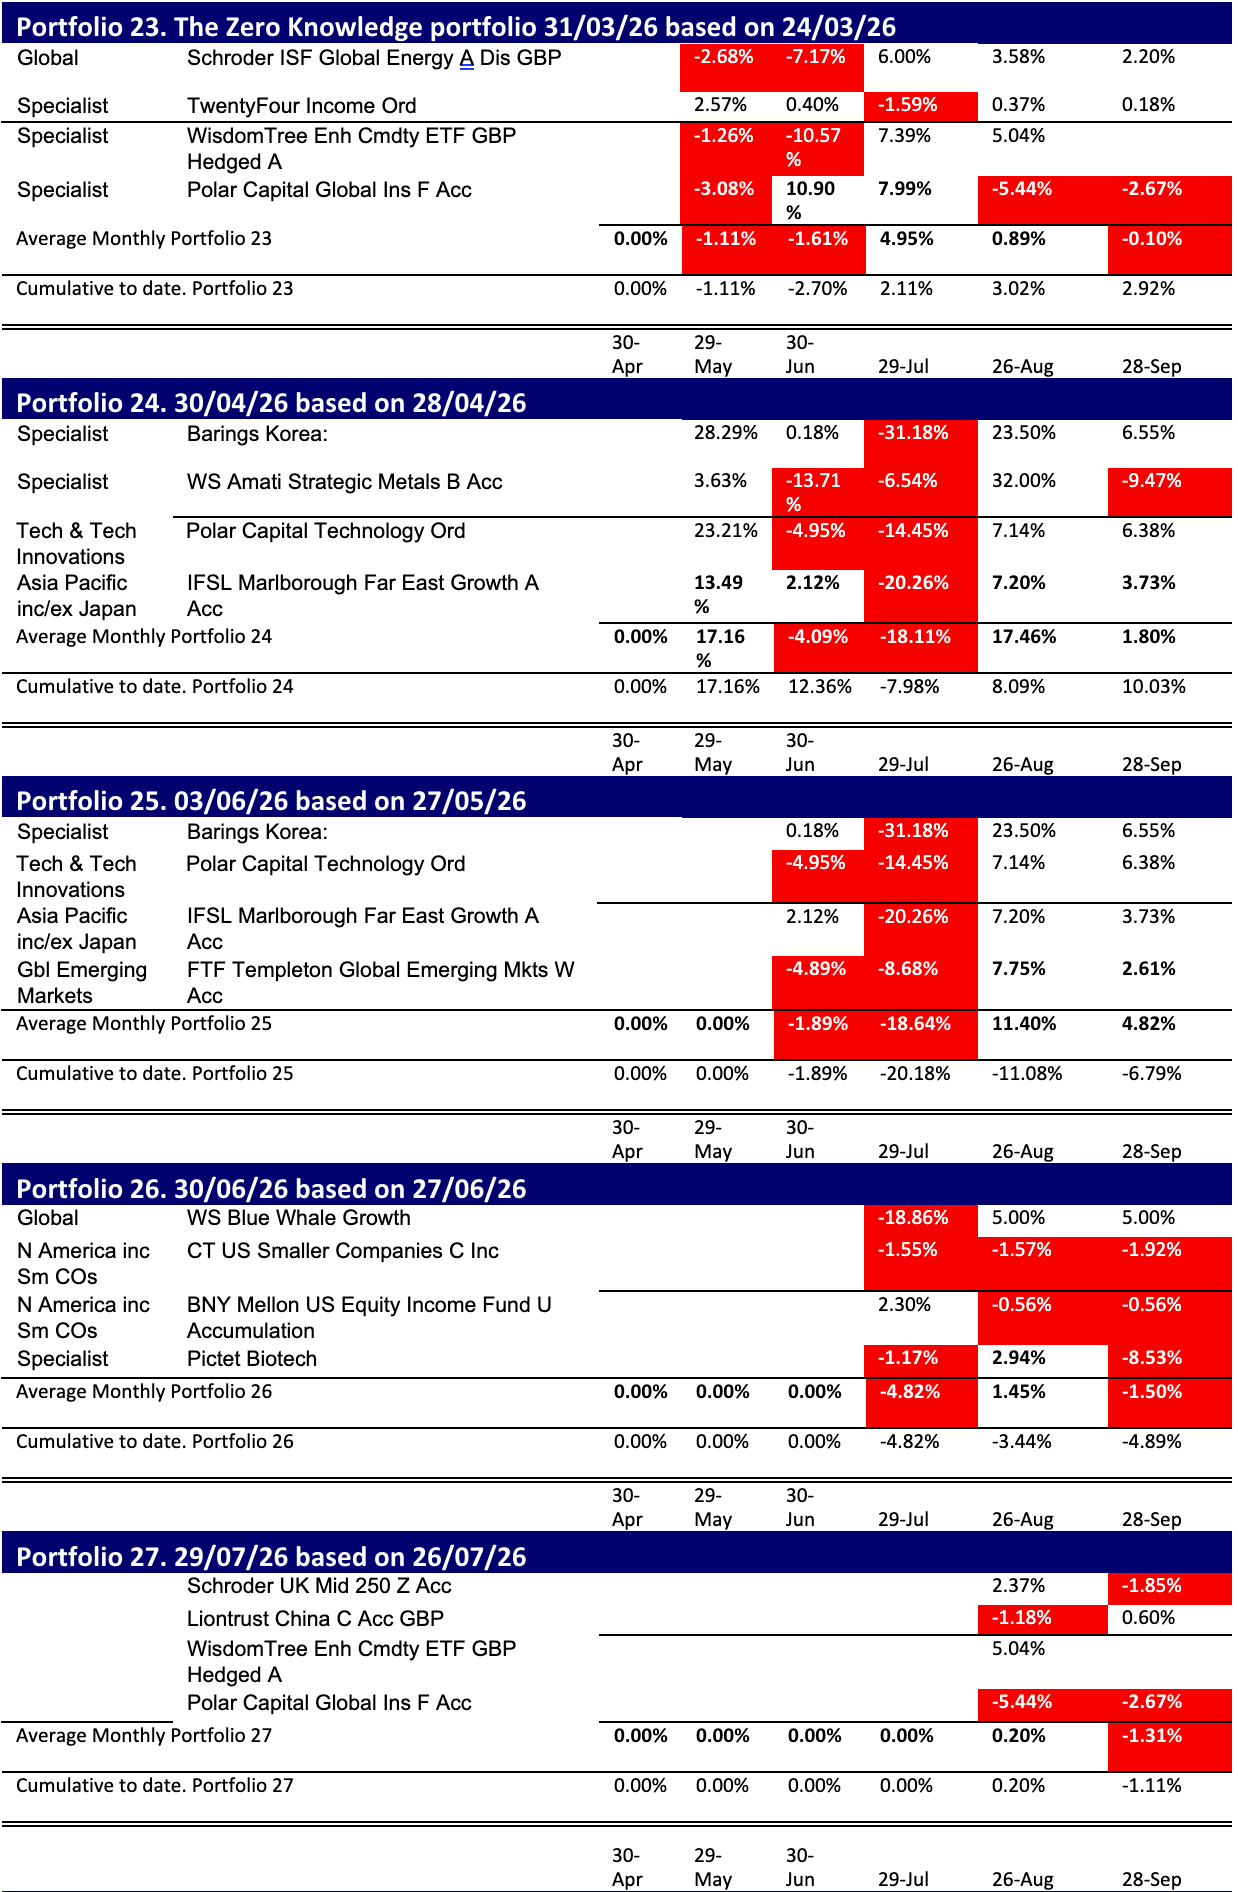
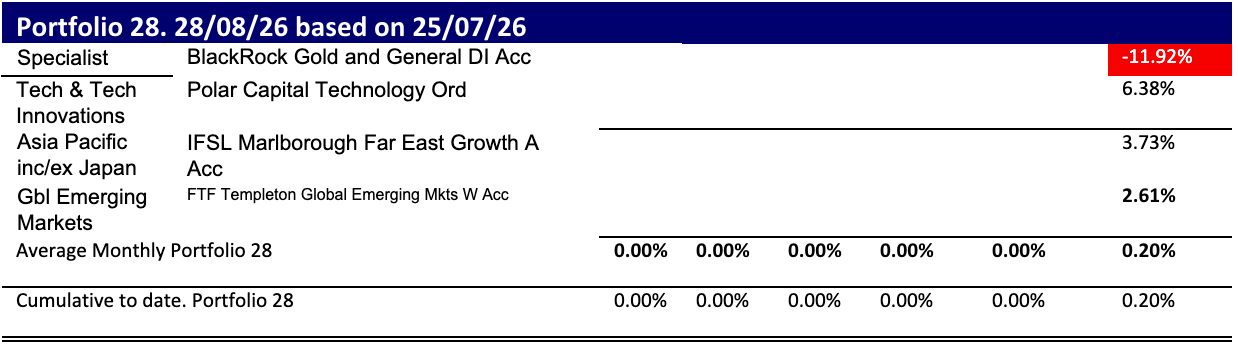
The strategy has underperformed the SWDA again, that’s four out of six months. Only portfolio 24 containing Korea (high chip) exposure, polar capital and gold has managed to find the combination of assets to beat the US heavy, tech heavy SWDA.
Once again (and again!), perhaps what we have done is to show that in the longer run, rather than a high-risk strategy like momentum, were we normal investors, we would be better served by leaving a substantial piece of our portfolios in SWDA! Winning the Losers game (to quote the author Charles D. Ellis)!
The ghost at the feast for SWDA is the AI boom. Will AI – whilst becoming the most transformative technological breakthrough since the steam engine – suffer a huge re-evaluation by the market. What might potentially cause this?
- Revenue growth not meeting aggressive targets at Anthropic and OpenAI;
- capacity growing too fast hitting profits as lease payments mount;
- data centres get into funding trouble in 2027 as rates rise further;
- the efficacy of open-weight models, with tokens a fraction of frontier model prices, undermines the revenue projections of the hyperscalers.
- Some combination of the above.
Momentum in September and a new portfolio Twenty-nine
If we look at the momentum over the last four weeks, then the ranking would be.
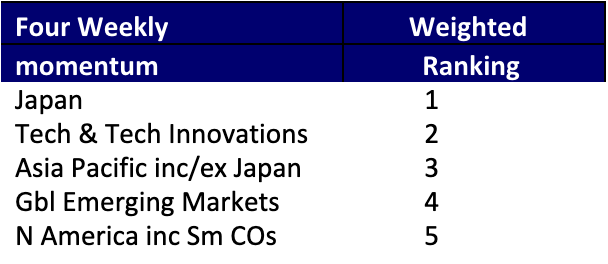
All up because of their tech focus. It is particularly instructive to look at the S&P500’s performance vs. the equal-weighted index. The mega caps are all the performance.
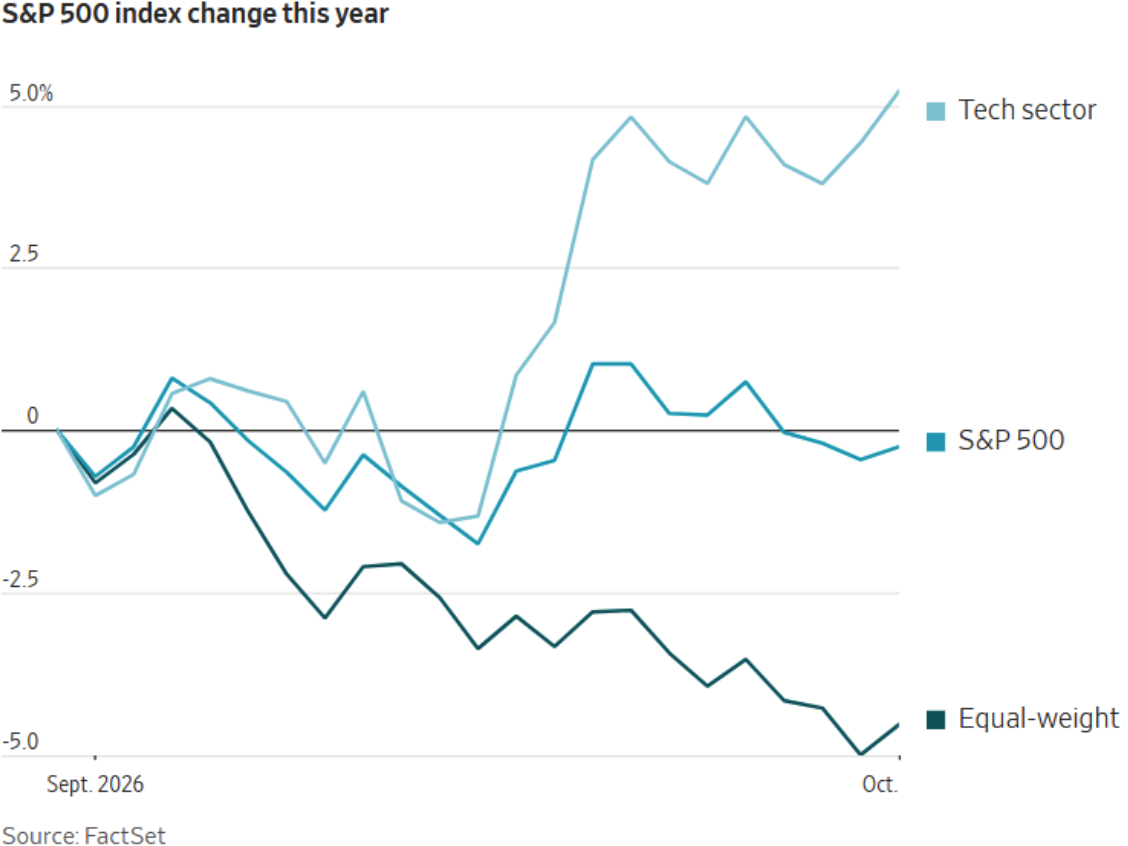
Which leaves us with a problem for October: all of the performance is tech related. So a bet on a high momentum segment is a disguised bet on chips and AI.
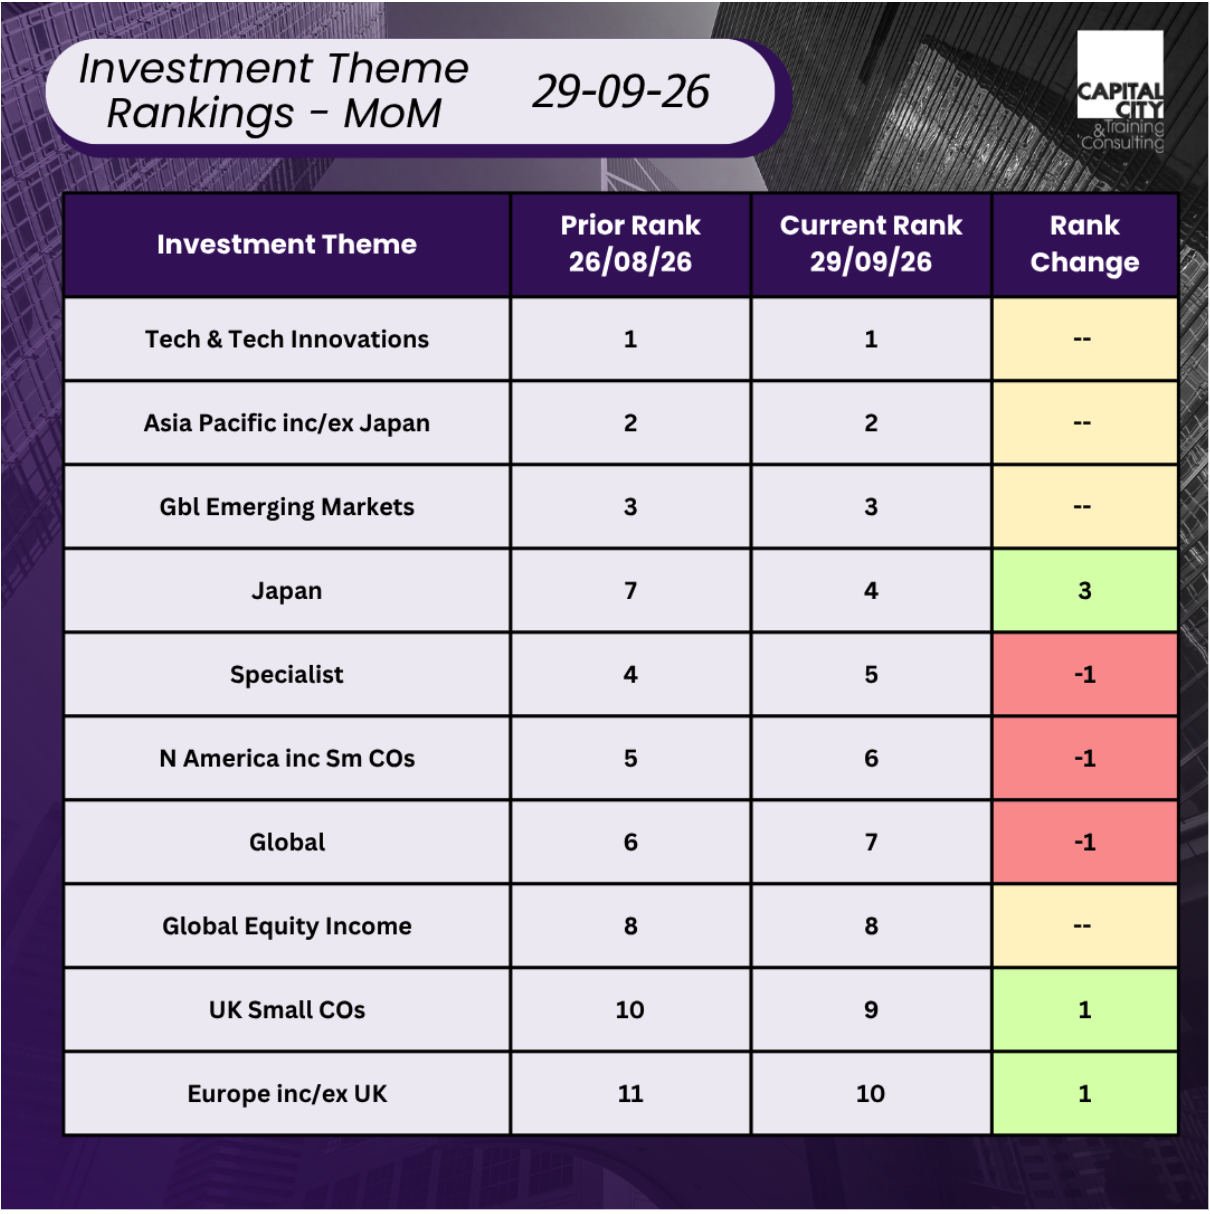
Like last month, I personally find it very difficult to come up with diversified momentum themes at the moment – but in the spirit of the experiment, I will propose a momentum portfolio, if a very concentrated one. Perhaps only for the very brave! I don’t usually bother making this point, but this is not investment advice! Personally, I have took a lot of money off the table over the last two months and put it into money markets. A time to sleep easy rather than sweat the news!
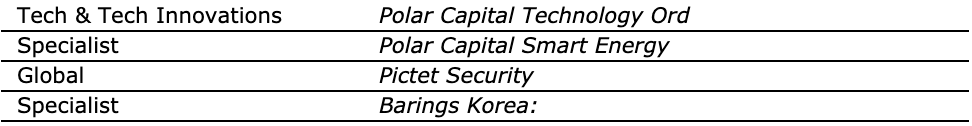
This month’s Positive momentum portfolios
find us on substack & Youtube
access the data for yourself